
Hello,
Welcome to Known Unknowns, a newsletter where happiness is linear in income.
There is a new Sheriff (or ref) in town
There are at least two things I have changed my mind about in the last five years: drug legalization and overly transparent monetary policy. Kevin Warsh had his second press conference and the bond market went wild, at least for a day or two.
So much for forward guidance, so much for publishing explicit forecasts. We don’t even have the stuffed briefcase Greenspan carried to speculate on, though maybe if Warsh has carpal tunnel that will tell us something.
But I am OK with this. I used to think transparency enhanced credibility and enforced rules over discretion. But really forward guidance became discretion in the short run, rules in the long run, and that does not make much sense. Nor does it help with credibility—in fact it may undermine it. Do we really need to know that the Fed can’t predict the future any better than the rest of us?
It seems we need to believe the Fed has more control over the economy than it does—that it can pick an inflation rate, that it can control the labor market. And it certainly has some influence, but not as much as people think. To some degree, its influence rests on the perception of its power, and the less we know what it’s thinking, the more powerful it can be. There is only one thing worse than not knowing the future, and that is expecting one thing and believing someone is in control, when they really aren’t. Let’s put the risk back in risk premium.
Also, I am confused why a rate hike is suddenly a done deal. A few months ago, it was still, “maybe the Fed should cut.” The labor market is not that much stronger since then. Yes, inflation progress has stalled and even reversed, but that is mostly due to supply-side issues, not a spike in demand.
It seems part of the reason long term yields are up is that everyone is waking up to what has long been true. The Fed has given up on its target, and we now have a 3%-ish inflation world. I guess we won’t have dot plots to tell us the Fed wishes that wasn’t true anymore. But that dot plot was starting to feel like an unrealistic vision board, and how does that help anyone?
Welcome to reality.
Rich and unhappy
It is the paradox of our time. By almost every measure, neoliberalism delivered. People all over the world are richer—not just in developing countries, almost everyone has much better and higher living standards. And yet, we constantly hear that people feel the economy is not working for them. Some are even thinking socialism is better.
Maybe it’s because there are diminishing returns to prosperity, maybe our rising incomes aren’t rising fast enough to meet our increased expectations, maybe some critical services like housing or health care are much more expensive. Maybe too many people in media who set the conversation are losing a zero-sum battle for positional goods in big cities with private equity bros. Maybe technology is making us crazy. Maybe the China Shock made things cheaper and created many new jobs, but also destroyed communities, and that’s what really matters. Or, as I argue in the new book, we’ve made it harder to take risks, and that deprives us of living a more authentic life, and that breeds dissatisfaction. Maybe it’s microplastics.
Or maybe everyone is just financially illiterate, and it is getting worse.
I am not sure it matters, because our response to many of these non-economic problems is to take a hammer to the prosperity we’ve built and make us actually poorer. If you think people are unhappy now, wait until they see what stagnation or even worse living standards looks like.
Home vs. stock market
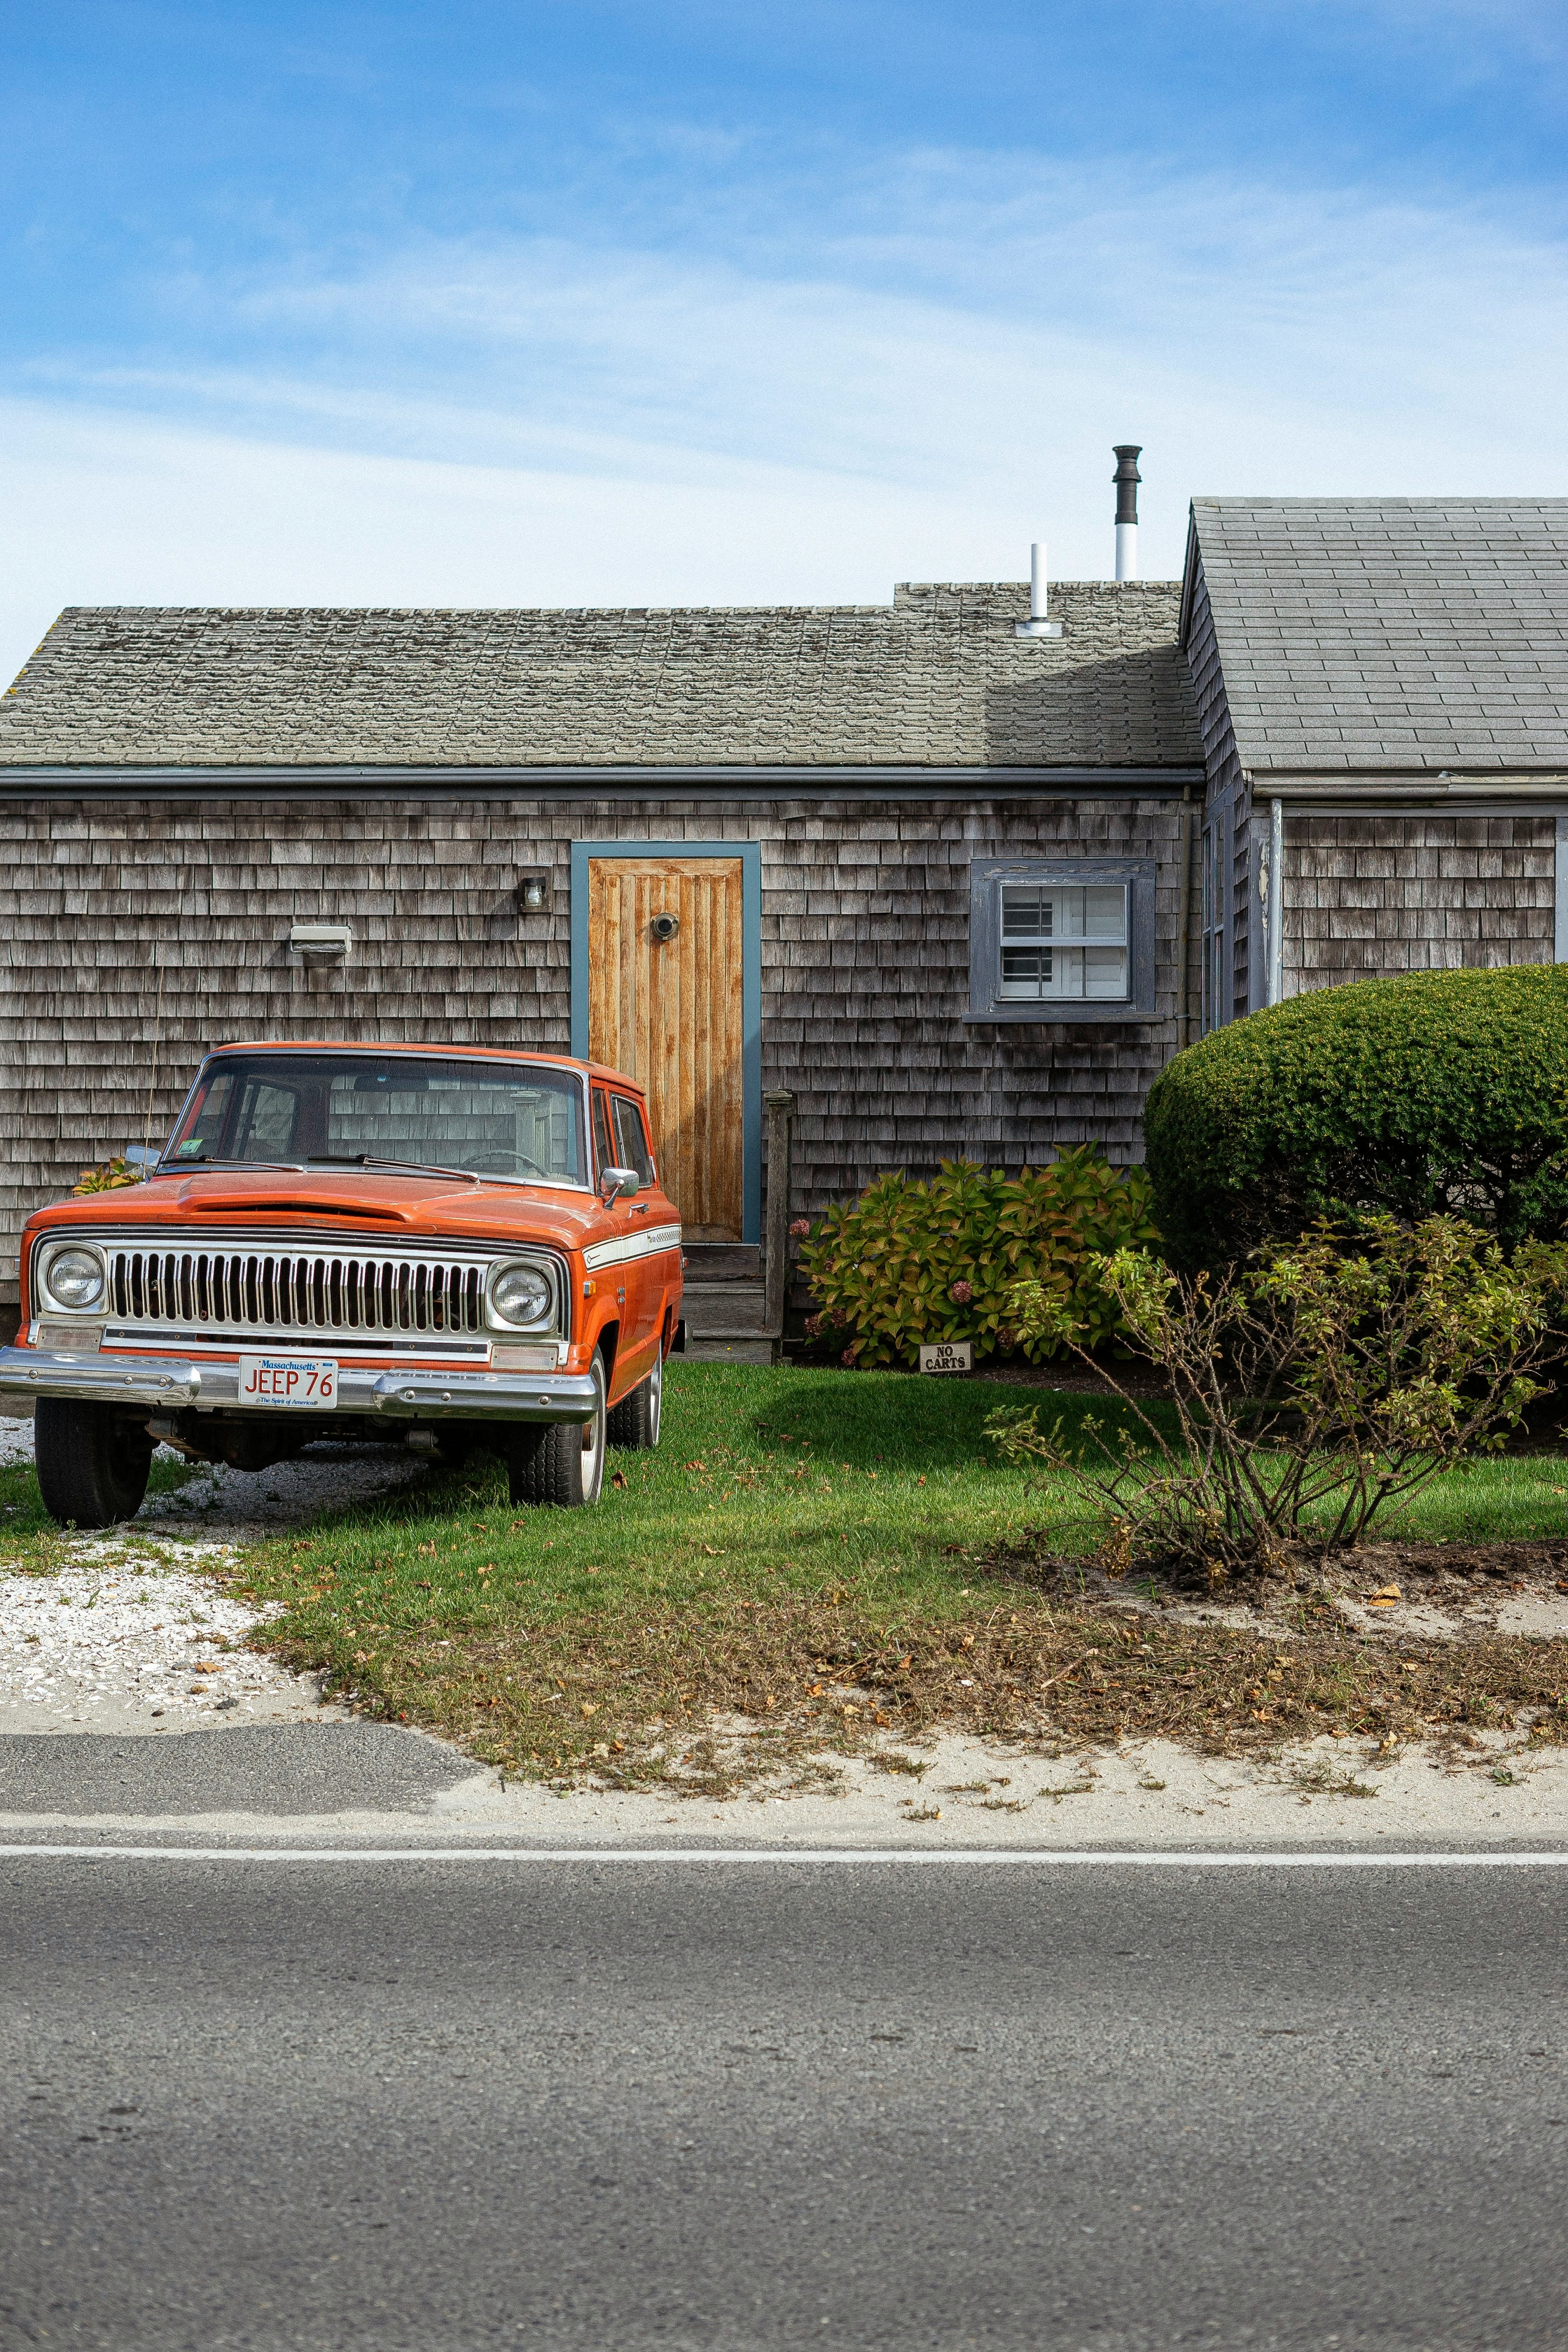
Here are some stunning statistics. In 1995 on Nantucket Island, the median house price was $500,000; now it is about $4 million. Home prices have gone up everywhere, but that seems extra crazy. But here’s something crazier: if you invested $500,000 in the S&P 500 in 1995, you’d have $8.4 million today! And that assumes you don’t reinvest the dividends, but because living in a house pays a dividend, we’ll leave those out.
Yes, I know leverage, taxes, and cost of living are also factors. But still. Maybe we need to drop this idea that buying a home is the ultimate financial goal. I always thought it was overrated, especially for young people. Maybe they shouldn’t be so unhappy they can’t afford to buy a house at age 25—the S&P doesn’t require a down payment and is liquid too.
Still, something is lost if we become a nation of renters with large financial portfolios. The American Dream was homeownership because you literally owned a piece of America; owning a piece of its best companies is also great. But it is, like many things in our lives these days, intangible and erodes community bonds—which does make us less happy even if we are richer.
Until next time, Pension Geeks!
Allison
Three nice reflections.
But I disagree about 1 and half disagree about 3.
Fed transparancy shoud be about what it thinks the economy will do given their decisions. It should NOT be about what the Fed itself may do in the future. Warsh has refused to give FG2 and that is good but also refused to give FG1, indeed has indicated he does not even know what FG1 would look like! PCE? Cosco prices? Something else?
Home ownership is a wortwhile goad because of the self discipline it imposes. You can always skip this months contribution to your mutual fund. That said, I do wish we encuraged non-house saving more with a progressive individual consuption tax instead f an individual income tax.
This. Thank you for a counter-argument having waded through so much litter of Op-eds this morning.